
Table of Contents
- Why Business Credit Repair Matters for Small Business Owners
- Disputing Errors on Business Credit Reports
- Business Credit Score Improvement Timeline and Realistic Expectations
- How to Build Business Credit from Scratch
Last Updated: August 15, 2026
Why Business Credit Repair Matters for Small Business Owners
Credit repair for small business owners is the process of identifying, disputing, and correcting inaccurate information on your business credit reports to improve your creditworthiness and access to capital. Unlike personal credit, business credit operates on a separate track, and most small business owners don’t discover damage until they apply for a loan and get rejected.
Your business credit score directly influences loan approval, interest rates, and available capital. A poor profile can lock you out of vendor accounts, equipment financing, and lines of credit, while also affecting payment terms with suppliers and your cash flow.
Repairing business credit differs fundamentally from personal credit repair. The bureaus, reporting rules, and timelines are different. Many owners waste months disputing errors on the wrong reports because they assumed the process mirrors personal credit. It doesn’t. At Honore Credit, we’ve worked with owners whose scores were tanked by old tax liens, duplicate trade lines, or vendor reporting errors. The good news: business credit is often more forgiving, errors are more straightforward to dispute, and rebuilding happens faster once you understand the system.
Disputing Errors on Business Credit Reports
The first step is pulling your actual business credit reports and identifying errors. Most owners have never seen theirs and don’t know what’s on it.
Business credit reports come from three main bureaus: Dun & Bradstreet (DUNS), Equifax Business, and Experian Business. Each maintains separate records and can contain different errors. You need to check all three.
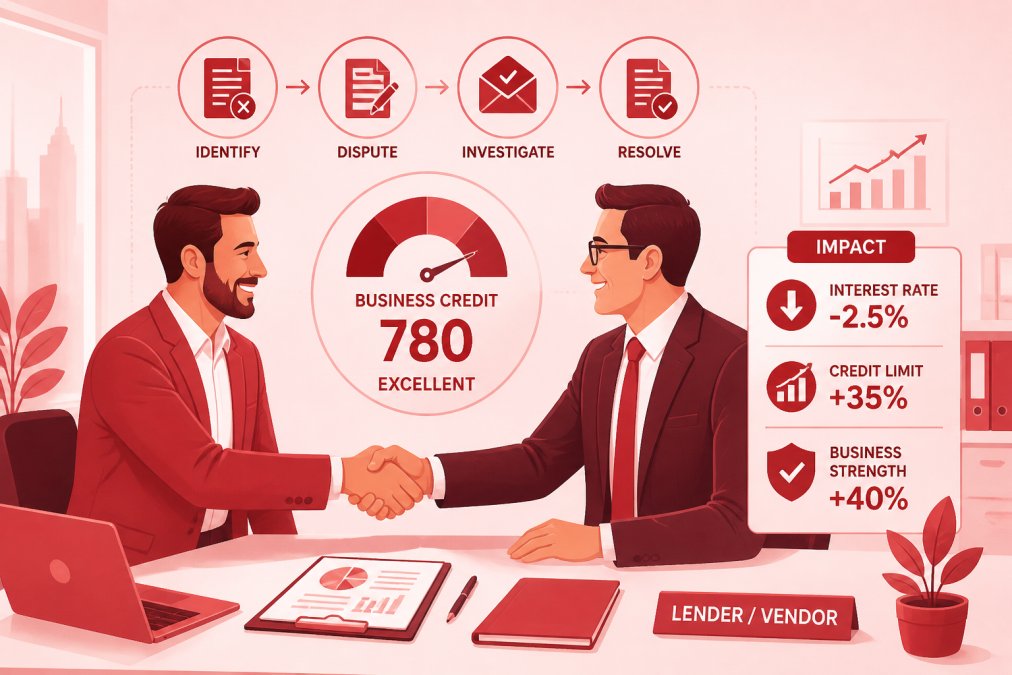
Once you’ve identified an inaccuracy, contact the credit bureau and provide documentation proving it’s wrong, a bank statement showing payment, proof of account closure, or evidence that a public record has been satisfied. The bureau has 30 days to investigate and respond. If they can’t verify the information, they must remove it.
Bureaus often reject disputes if documentation doesn’t match their standards. If disputing a tax lien, for example, they want the lien release from the tax authority, not a letter from your accountant. Being specific and thorough dramatically increases success rates. Also avoid disputing the same error multiple times in a short window, bureaus flag repetitive disputes as frivolous. Space disputes strategically and focus on the most damaging inaccuracies first.
Business Credit Score Improvement Timeline and Realistic Expectations
Rebuilding business credit takes patience. Most owners should expect 3 to 6 months of consistent work before seeing meaningful score movement.
The timeline depends on what you’re fixing. Disputing inaccurate information typically takes 30 to 45 days. Rebuilding from scratch by establishing trade lines takes longer, as new accounts need time to report and age before significantly boosting your score.
If your business credit is severely damaged, you won’t jump from a 400 score to a 700 in three months. What you will see is forward momentum: errors removed, new positive trade lines reporting, and a downward trend reversing. Lenders notice that trajectory even if your absolute score is still modest.
Avoid applying for multiple lines of credit at once to speed rebuilding. Each application generates an inquiry, and too many in a short period signal financial desperation to lenders. Space applications out and focus on one or two trade lines at a time.
How to Build Business Credit from Scratch
If your business is brand new or your credit is severely damaged, establish trade lines, documented credit accounts that report to business bureaus.
Start with vendor accounts. Contact vendors in your industry and ask about opening a business account with payment terms (net 30, net 60, etc.). Local vendors are often more flexible than national chains. Once approved, use the account, pay on time, and let the vendor report your payment history to the credit bureaus.
Next, consider a business credit card. A secured business credit card (backed by a cash deposit) is often easier to qualify for than an unsecured card. Use it for small business expenses and pay the balance in full each month.
Installment loans also build credit history. A term loan from a bank or credit union, even a small one, diversifies your credit profile. Lenders like seeing that you can handle different types of credit responsibly.
The key is consistency. Make every payment on time. Payment history is the single most important factor in your business credit score. One missed payment can undo months of rebuilding work.
Rebuilding your business credit takes strategy, but it’s entirely within your control. Errors can be fixed, missing trade lines established, and damaged scores improved. The real barrier isn’t complexity, it’s understanding what to do and staying consistent. Many small business owners benefit from professional guidance to navigate the bureaus, prioritize disputes, and avoid costly mistakes. Services like those offered through Honore Credit’s Credit Approval Plan provide tailored strategies for business credit repair, helping you move from financial uncertainty to the clarity and confidence you need to grow.
Frequently Asked Questions
How long does it take to rebuild business credit?
Business credit rebuilding typically takes 3 to 6 months to see meaningful score improvements, though the timeline depends on how quickly you address disputes, establish trade lines, and demonstrate consistent payment history. Significant damage like tax liens or judgments may take 12 to 24 months to fully recover from. The key is starting immediately: every month of positive payment activity strengthens your creditworthiness and financial stability.
What's the difference between personal and business credit?
Personal credit is based on your individual financial history and reported to consumer credit bureaus. Business credit is tied to your company's EIN and reported to business credit bureaus like Dun & Bradstreet and Experian. Business credit is separate from personal credit, meaning you can establish strong business creditworthiness even if your personal credit is damaged. This separation is essential for small business owners seeking capital access and loan eligibility without personal guarantees.
Is it worth paying a professional to fix business credit?
Professional credit repair services can be worthwhile if you lack time, expertise, or success disputing errors yourself. Professionals know the dispute process, understand credit report analysis, and can identify inaccuracies you might miss. However, you can dispute errors independently by contacting credit bureaus directly. The ROI depends on your timeline: if you need improved creditworthiness within months for funding, professional guidance accelerates results and increases loan eligibility chances.
How do I establish trade lines for my business?
Trade lines are vendor accounts and revolving credit accounts that report to business credit bureaus. Start by opening a business bank account, then apply for a business credit card and make small purchases you pay off monthly. Contact vendors who report to credit bureaus and request net-30 or net-60 terms. Each on-time payment builds your payment history and improves your business credit score. Establish 3 to 5 trade lines for strong financial health and creditworthiness.
This article was written using GrandRanker